
 Tech & AI
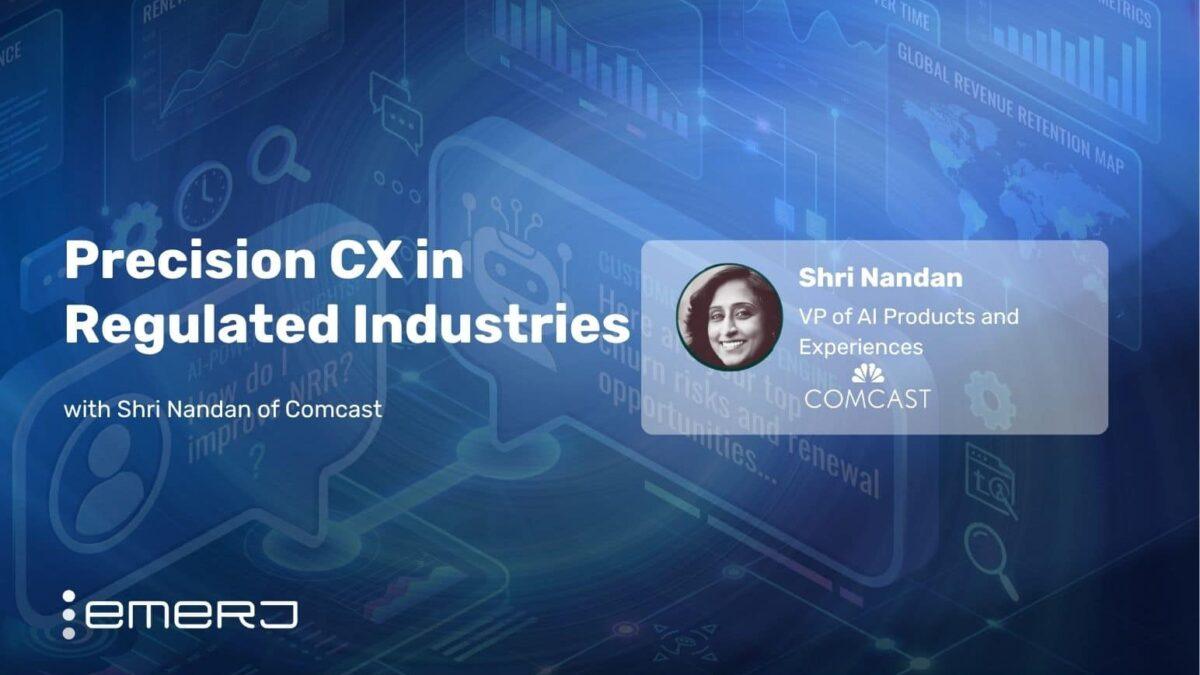
Customer service has become an early testing ground for AI in banks, insurers, and healthcare organizations, according to the U.S. Government Accountability Office. In financial services, all ten of the largest U.S. commercial banks now deploy chatbots, and more than 98 million consumers interacted with one in 2022, per the Consumer Financial Protection Bureau. The CFPB cautions that poorly designed bots can give wrong information, miss when consumers exercise federal rights, and block access to human representatives. Healthcare reveals a similar gap between adoption and readiness. 71% of U.S. hospitals use predictive AI, and the share applying it to scheduling jumped from 51% to 67% in a single year, according to the Office of the National Coordinator for Health IT. Yet 77% of health system leaders call immature AI tools their top adoption barrier, with regulatory uncertainty at 40%, per a survey in the Journal of the American Medical Informatics Association. Oversight itself is struggling: the GAO found the federal agency supervising credit unions lacks tools to oversee their AI use, leaving a gap between deployment speed and governance. Yolandi de Weerdt of Emerj recently spoke with Shri Nandan, VP of AI Products and Experiences at Comcast, about scaling AI in regulated industries by grounding CX in governance, clean data, and clear human-AI boundaries. Three insights matter most for CX, digital, and AI leaders in banking, insurance, and healthcare. Much AI customer service optimism assumes a generic enterprise setting. Nandan notes that BFSI and healthcare differ in kind, starting with emotional context. An agent helping someone buy insurance handles a transaction; one addressing why a patient needs an appointment may handle something far more sensitive. That difference must shape system design before coding begins.
She argues the decisive step is an honest, explicit discussion about what AI should do for the customer—and where it must stop. “When you’re designing your agentic system, there has to be an honest discussion about what it is that you want your AI to do to help the customer,” she said. “Is it just scheduling and rescheduling appointments, or is it something fairly simple, like looking at your lab work results? If it’s a little bit more complicated, especially in things like oncology or something more serious than that, how would you expect AI to help the customer? I think it’s important for the organization to understand that there isn’t a lot that AI can do in certain situations, and you need human intervention.” Financial services raises a parallel risk problem. Nandan described the appeal of an AI financial advisor and the follow-up question: how does the institution know the advice is sound, and how does it know the agent has considered every option that could earn more for the customer? Building an agent that far-reaching, she said, is harder than it appears.