
 Fintech
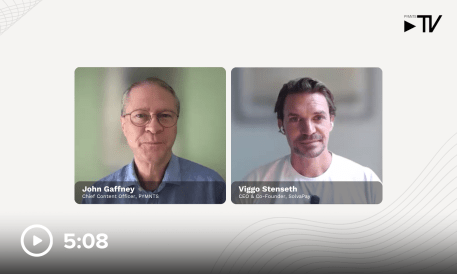
The payments industry has long focused on preventing bots from impersonating customers. But agentic commerce introduces a twist: some bots are authorized to buy. SolvaPay, a Stockholm-based fintech, is developing payment infrastructure specifically for AI agents. Its solutions include machine-readable payments, usage-based billing, and transactions between agents, along with spending controls. CEO and co-founder Viggo Stenseth sees payments as a collision point between AI’s growing autonomy and systems designed for humans. “We built really robust systems to verify that there’s a human doing the transaction, 3DS, CVV codes, everything to prevent a bad bot from doing things,” he said. “So, it’s really ingrained in the infrastructure.” Merchants can’t simply drop those safeguards; they must distinguish authorized agents from malicious software while determining whose money is being spent and what it can buy. Stenseth compares the current moment to the early internet era, when businesses were skeptical of e-commerce. But agentic AI is evolving much faster. “The timer already started a couple of years ago,” he said. While agents can already perform tasks autonomously, “the billing, the payment, the flow hasn’t really been solved yet.”
Agent transactions differ from human ones. A single assignment can spawn multiple payments as agents delegate tasks to other agents, creating layers of transactions. “We’ve built systems around, like, doing reconciliation or solving one single transaction,” Stenseth noted. If something fails deeper in the chain, it’s unclear whether to roll back everything or just the failed part. Agents can also act as both buyers and sellers. Stenseth describes a developer whose financial analysis agent paid external data providers for information, then resold its enriched analysis to others. Such scenarios favor usage-based charges for API calls, datasets, or services over traditional subscriptions. “People building with agents are already more accustomed to usage-based billing,” Stenseth said. Yet agent payments must still connect to the established financial system, with all its anti-money laundering rules, ledgers, licensing, and security. “You can’t skip steps,” Stenseth emphasized. For merchants, this means updating fraud detection, billing, and reconciliation processes. Eventually, agents might even choose payment methods—optimizing for rewards or other goals—on behalf of consumers.